Credit Cards and Everyday Banking in Malaysia: Fees, Rewards and Apps

Person using a laptop beside a credit card on a wooden table

Cards, current accounts and apps are one money system

Malaysian everyday banking is no longer a passbook-only habit. Credit cards, current accounts and phone apps sit in the same week: salary lands, bills leave, rewards accumulate, and a balance check happens while you wait for coffee. The risk is treating each product as a separate toy instead of one cashflow system.

A retail bank’s credit card product range is a good place to study fee tables and reward rules before you chase a welcome bonus. Annual fees, foreign exchange mark-ups, interest on revolving balances and how categories earn points all change the true cost of “free” perks.

If you already revolving a balance, new rewards rarely outrun interest. Pay that down first; comparison shopping is more honest when the card is a payment tool rather than a high-cost loan.

Read the card like a contract, not a lifestyle ad

Cashback and miles ads highlight the upside. The quieter lines cover late fees, minimum payments and what happens if you miss a due date. Financial Education Network guides keep returning to the same discipline: know the instalment you can clear in full, and treat revolving interest as a last resort.

Match the card to your actual spend. A petrol-heavy category is useless if you barely drive. A travel card is expensive theatre if you fly once every three years. Category fit beats brand prestige for most households.

A plain primer on how card balances, due dates and interest interact.

Current accounts still do the unglamorous work

Salary credits, spousal transfers and bill automations usually live in a current account. Looking at everyday deposit account choices at the same bank helps you check service charges, minimum balances and whether the account plays nicely with the card you already hold.

Auto-pay arrangements reduce missed bills, yet they also hide rising subscriptions. Review the list quarterly. A tidy account history is useful when you later apply for financing; unexplained overdrafts are not.
Two people at a wooden table reviewing a printed form with a pen and a phone, beside a calculator and a white mug
Cashflow clarity matters more than collecting every new product badge.

Digital access is a security habit, not only a login screen

Many banks now push customers toward app-first journeys. The bank’s main consumer banking homepage is often where digital account entry points, security notices and product updates appear together. Treat that hub as an operations panel: enable notifications, review device bindings, and be wary of links that arrive by SMS.

Agensi Kaunseling dan Pengurusan Kredit remains a practical stop when debt stress outruns DIY budgeting. Early counselling is cheaper than collecting more cards to paper over a shortfall.

Also skim Bank Negara’s financial consumer alert list when a “bank officer” calls asking for one-time passwords. Real banks do not need you to read OTPs aloud on the phone.

Keep a short written map of which account pays which bill, and which card is reserved for large planned purchases. Households that share money without a shared map tend to double-pay or miss renewals. A one-page note on the fridge still beats three conflicting chat messages.

Foreign currency spend deserves its own line in your notes. Dynamic currency conversion at overseas terminals often looks convenient and quietly costs more than letting the Malaysian bank convert at its published rate. Decline the merchant’s local-currency offer when you understand the card’s FX fee; the cheaper path is not always the one the terminal highlights first.

Joint households should agree who watches which due date. Duplicate card products in one family can create overlapping annual fees for little gain. Sometimes the better upgrade is a single well-understood card plus a plain account, not a drawer of plastic.

When offers arrive by email, open the bank app or typed URL yourself rather than tapping the message link. Phishing copy has become fluent in Bahasa and English; urgency language about “account suspension” is a classic tell.

A simple monthly rhythm

Pick one day each month to clear card balances you mean to pay in full, scan current-account fees, and delete unused app sessions on old phones. Everyday banking gets safer when it is boring and regular. Rewards are a side effect, not the plan.
What to clarify at a Kuala Lumpur fertility centre visit

Young couple consulting two clinicians at a white desk in a bright clinic office

Begin with definitions, not outcome promises

Adults in Kuala Lumpur often arrive at a fertility discussion after months of trying to conceive, irregular cycles, prior surgery, or a wish to understand options such as IVF or egg freezing. Useful conversations start with definitions, history, and a test plan. They do not start with guaranteed pregnancy percentages on a homepage banner. No clinic can promise a specific outcome for every person, and treating marketing language as clinical evidence leads to poor decisions.

The WHO fact sheet on infertility frames infertility as a disease of the reproductive system and emphasises access to information and care. CDC materials on assisted reproductive technology (ART) explain how clinics report procedures and outcomes in aggregated form. ASRM patient education on planned egg freezing stresses age effects and the absence of guarantees. Read those frames before you compare local centre pages.

Young couple consulting two clinicians at a white desk in a bright clinic office
Keep the first visit factual: history, tests ordered, and an options map without outcome promises.

What a centre visit is for

A first visit usually gathers reproductive and medical history, reviews prior labs or imaging, and proposes a diagnostic sequence. Ask which tests are being ordered, why each one matters, whether a partner needs concurrent testing, and when results return. A neutral reading of this fertility centre overview should help you see service scope and locations without treating any brand ranking language as evidence of better outcomes.

Bring a timeline of cycles, medications, surgeries, pregnancies, and prior fertility care. Write questions in advance about male-factor testing, ovarian reserve markers, uterine or tubal evaluation, and when expectant management is still reasonable. These are medical decisions about adult bodies and futures. Keep the tone factual in the room even when emotions are high afterward.

How an IVF pathway is typically organised

IVF generally includes ovarian stimulation with ultrasound and blood monitoring, a trigger injection, egg retrieval under sedation, laboratory fertilisation (sometimes with ICSI), embryo culture for several days, and transfer timing decided with the clinical team. Success rates vary by age, diagnosis, embryo stage, laboratory practices, and many other factors. When you read an IVF treatment pathway in Malaysia page, look for process steps, counselling notes, and what is included in quoted packages rather than slogans.

Ask how the clinic explains its own audited statistics, which years and age bands those numbers cover, and what happens if a cycle is cancelled for medical reasons. Multiple cycles may be discussed; that is planning, not a promise that the next cycle will succeed.

Related watch: Cleveland Clinic step-by-step IVF explanation for patient education.

Egg freezing as preservation, not a promise

Egg freezing follows a similar stimulation and retrieval sequence, then vitrifies mature eggs for later use. Later thawing often relies on ICSI because the egg coat can harden after freezing. Age at freeze strongly influences later possibilities, and not every egg survives thaw or becomes a viable embryo. Use egg freezing facts to review before a consult as a discussion aid with a specialist, not as a self-diagnosis or timeline guarantee.

Clarify storage consent duration, annual fees, and what happens if you move countries. Preservation buys options under uncertainty. It does not freeze a calendar outcome.

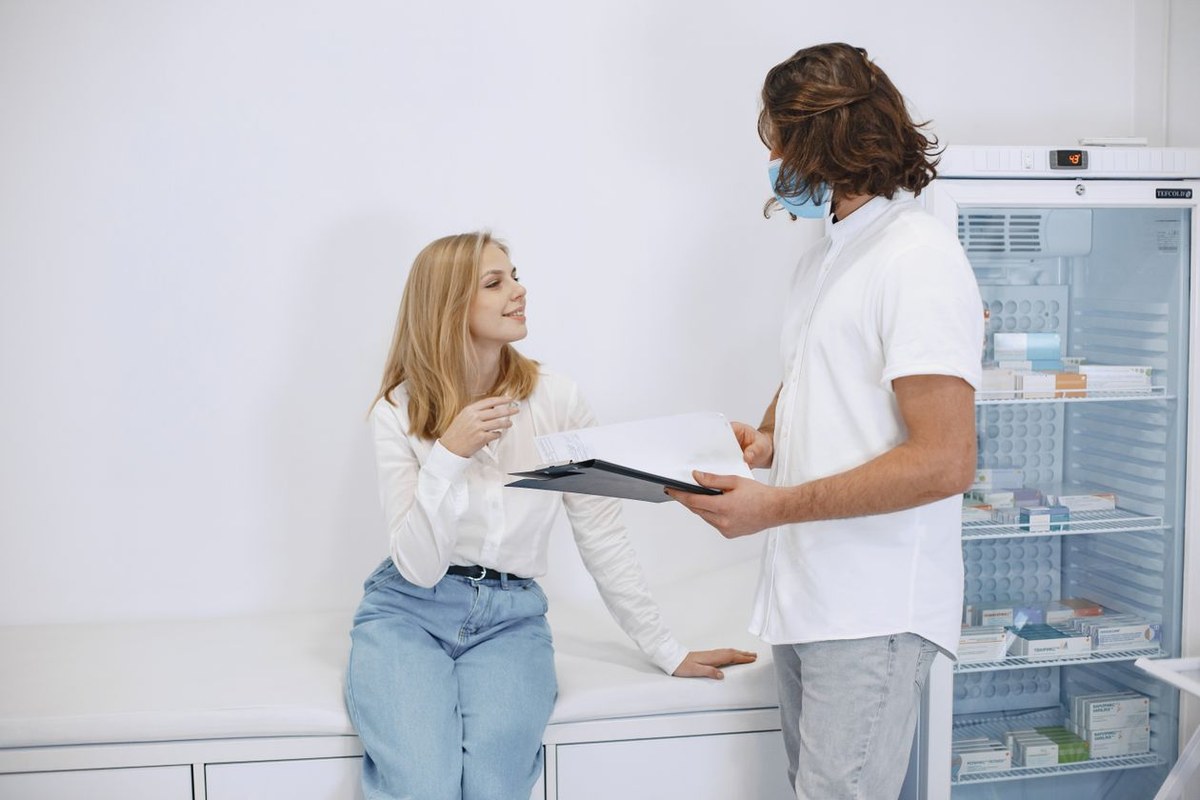
Patient on an exam bench talking with a masked clinician holding a clipboard beside a medical fridge
Both paths need counselling and written next steps; freezing stops before fertilisation and transfer.

Questions that keep the next appointment grounded

Leave with three written items: the working diagnosis or “still investigating” status, the next test or treatment step with a date, and the risks or uncertainties the clinician named in plain language. If cost schedules are discussed, ask what is included versus optional add-ons, and how cancelled or incomplete cycles are handled financially.

Revisit those notes when emotions run high between visits. Informational clarity is the point of this reading. Outcome guarantees are not, and no article should invent them.